Uncertainty Estimation
Quantile-based and distributional methods for calibrated, multivariate uncertainty.
A point estimate says little about what the data actually support. I develop methods for multivariate conditional distributions, in particular vector quantile regression built on optimal transport, that scale to large datasets and extend to manifolds. These give calibrated uncertainty that can inform downstream decisions, including what to measure next.
Selected work
2024
-
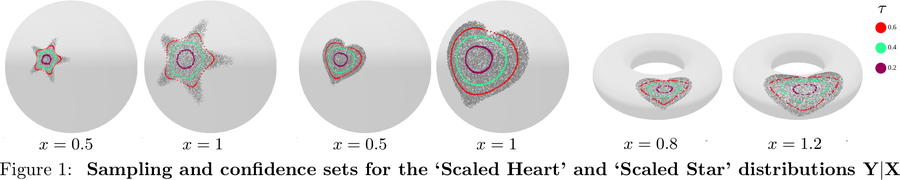 Vector Quantile Regression on ManifoldsProc. International Conference on Artificial Intelligence and Statistics (AISTATS)

2023
-
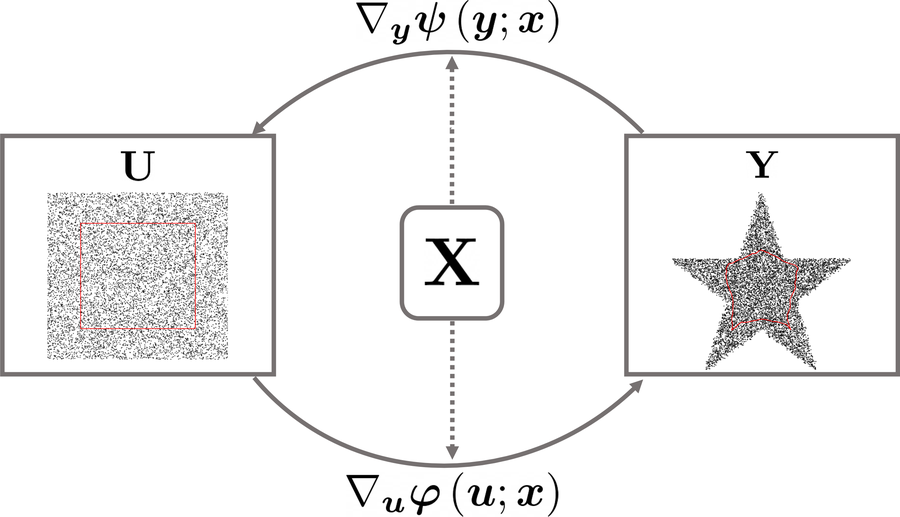 Continuous Vector Quantile RegressionICML Workshop on New Frontiers in Learning, Control, and Dynamical Systems
-
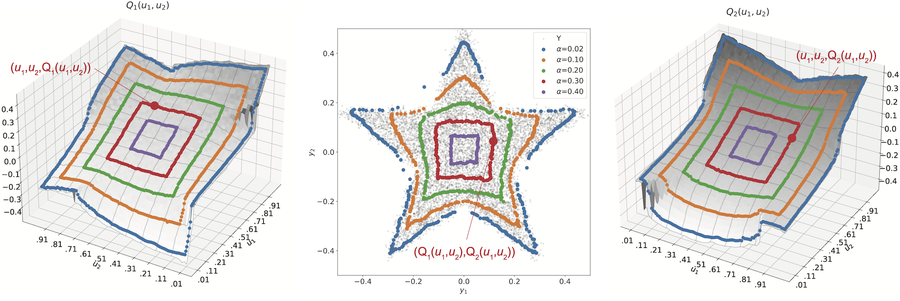 Fast Nonlinear Vector Quantile RegressionProc. International Conference on Learning Representations (ICLR)

